

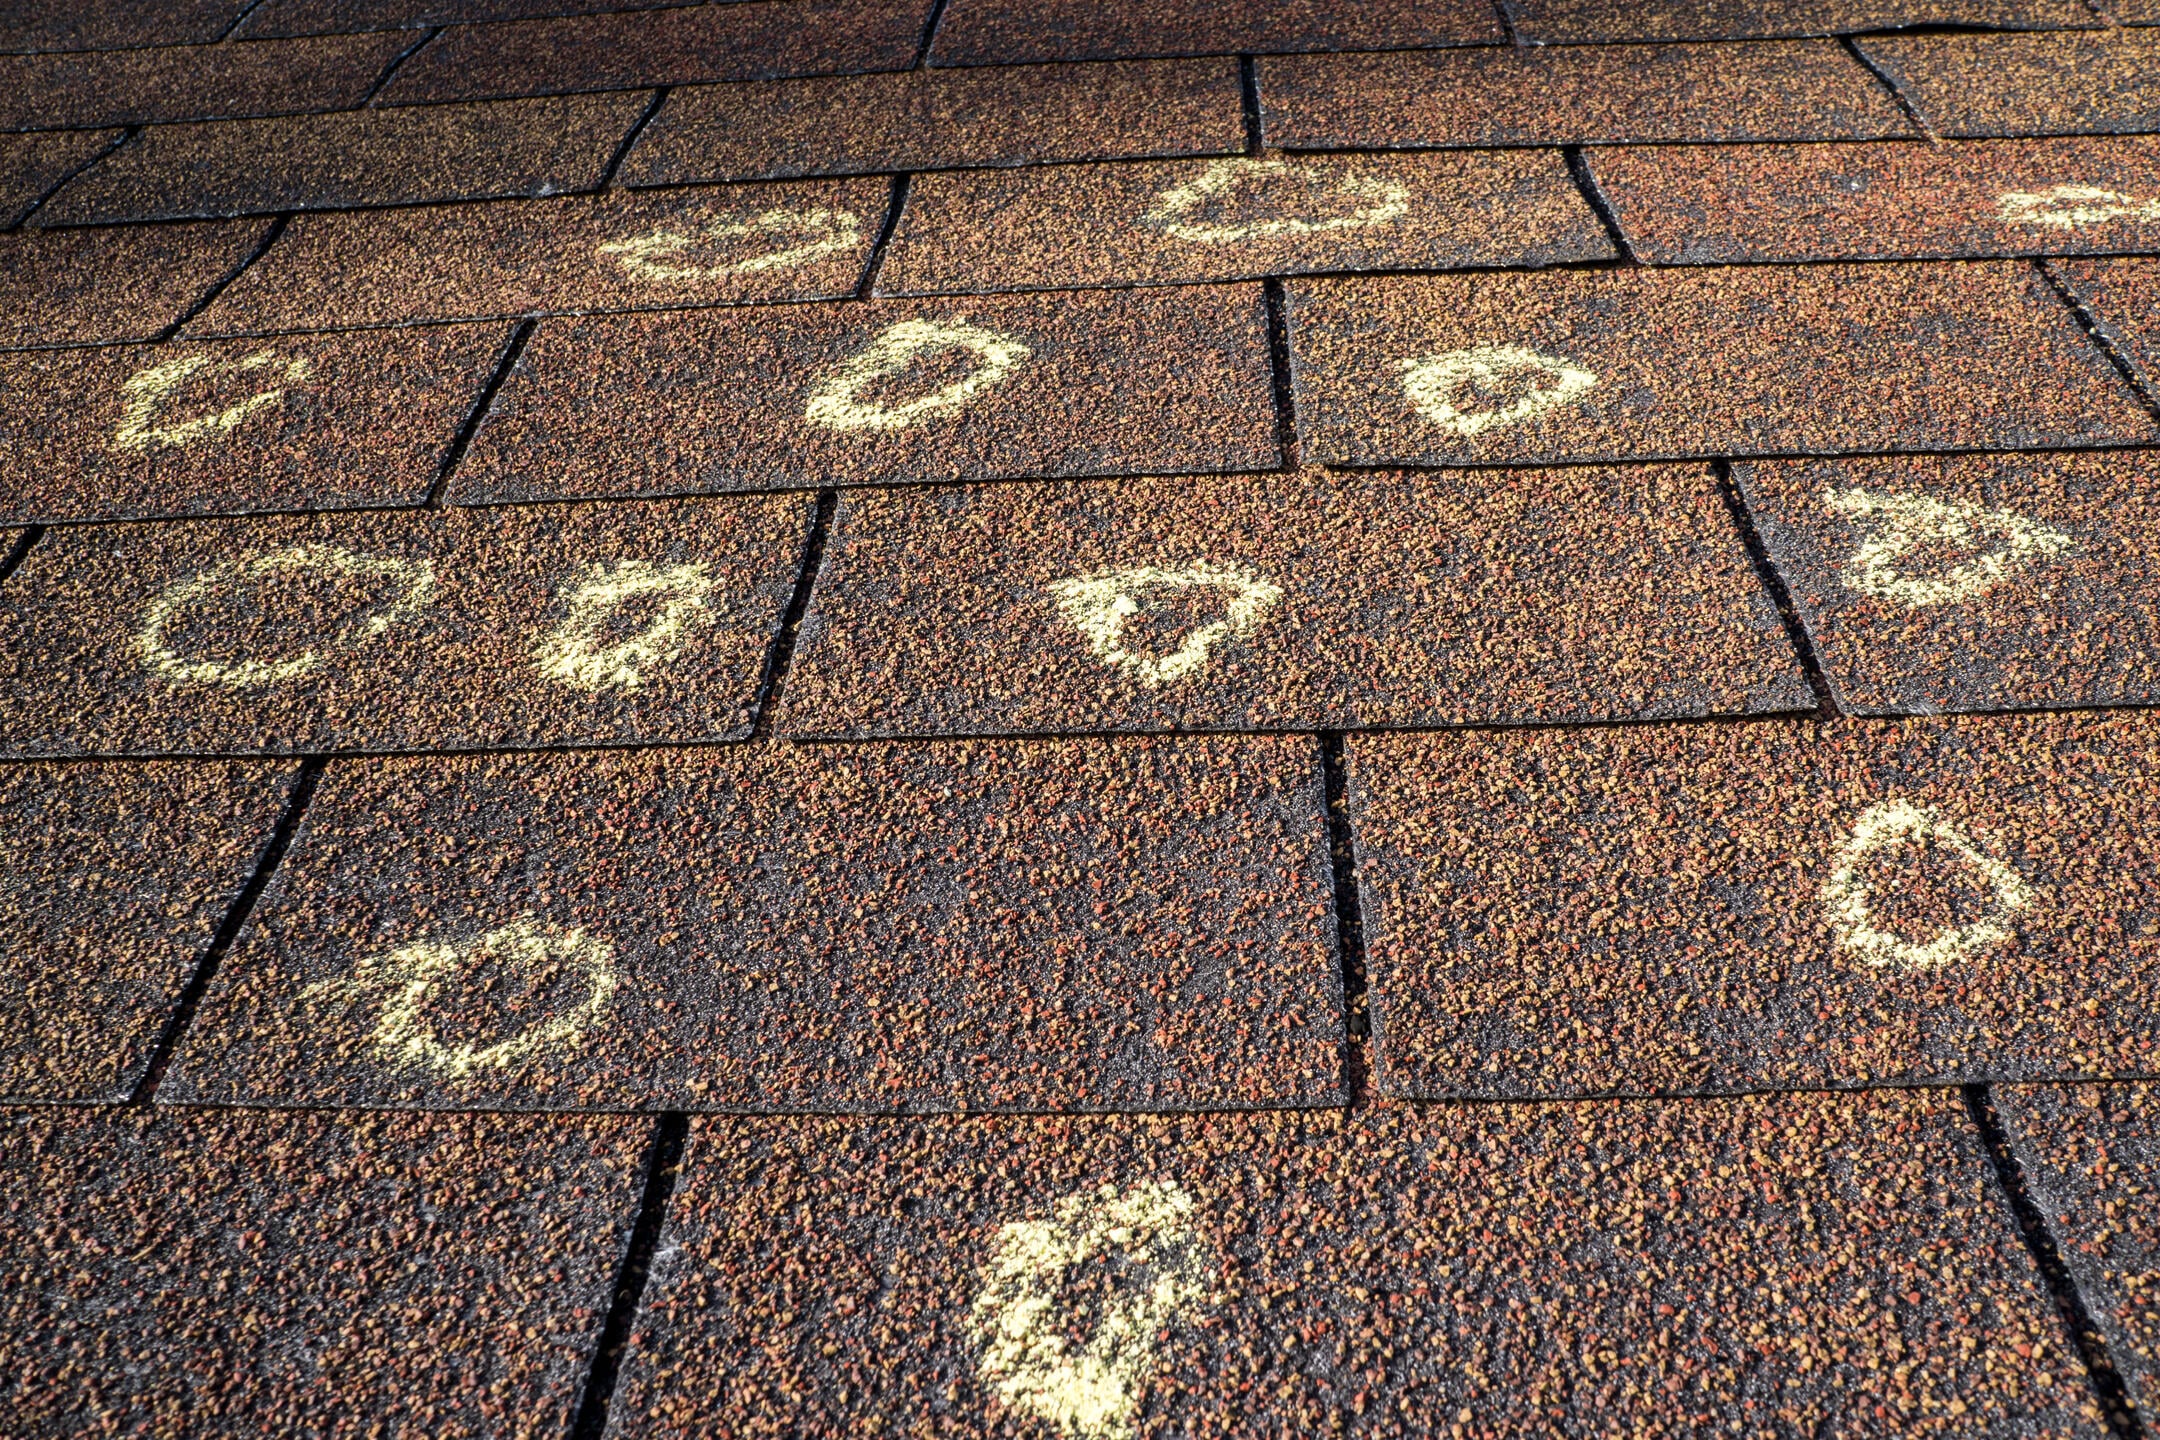
After a storm damages your roof, you’ll likely hear the word “adjuster” more times than you can count. But not every adjuster plays the same role, and understanding the public adjuster vs insurance adjuster difference can shape how your claim unfolds. One works for your insurance carrier, while the other works for you. If you’re focused on getting your home back to where it was before the storm, knowing who’s who helps you ask the right questions and make confident decisions along the way.
A quick look at what’s covered:
- What each type of adjuster does
- Six differences that matter most
- When hiring a public adjuster makes sense
- How your roofer fits into the process
Why Knowing Who Represents You Changes the Outcome
Property insurance claims are financial conversations, and it helps to know which side each person at the table is on. Many policyholders assume every adjuster is a neutral party, but that’s not how the system works. For homeowners in Johnson Creek and surrounding areas dealing with hail, wind, or ice damage, understanding the basics of hiring a public adjuster versus relying on your insurer’s adjuster can help you plan your next move.
Here’s why the distinction matters:
- Clearer expectations: Knowing who each adjuster works for helps you understand their priorities and how they’ll approach your claim.
- Better preparation: When you understand the process, you can gather documentation and evidence that supports a fair and reasonable settlement.
- Smarter cost decisions: Public adjusters charge a fee, and not every claim requires one, so knowing when their help is worth it keeps more money in your pocket.
- Less stress: A clear picture of everyone’s role makes a confusing process feel more manageable.
Neither type of adjuster is good or bad on its own. Each one serves a purpose, and the right choice depends on the size and complexity of your claim.
6 Key Differences Between Public and Insurance Adjusters
At first glance, both adjusters seem to do the same job: inspect the damage, review the policy, and estimate the cost of repairs. The core difference comes down to who hires them, who pays them, and whose financial interest they represent.
1. Who They Work For
An insurance company adjuster is assigned to evaluate your claim on the insurer’s behalf. A licensed public adjuster is a professional you hire yourself, providing professional representation throughout the claim.
2. How They Get Paid
Insurance adjusters are paid by the insurance company, either as employees or as contractors. Public adjusters are paid by you, usually through a percentage of the final settlement.
- Fees are typically taken from the insurance settlement
- Some charge a flat fee or hourly rate instead
- State law in some states caps how much they can charge
- Always review the fee structure before signing
3. When They Get Involved
Your insurer sends its adjuster after you report the damage, usually within days or weeks. A public adjuster can be hired at any point, whether at the very start of a claim or after you’ve received an initial offer that seems too low.
4. Their Main Goal
An insurance adjuster’s job is to evaluate claims according to the policy and company guidelines. A public adjuster’s goal is to document every covered loss and negotiate the strongest possible settlement for the homeowner. Both should be fair and accurate, but their perspectives naturally differ, which can lead to different estimates for the same damage.
5. How Much of the Process They Handle
The insurance adjuster handles the insurer’s side of the claim, from inspection to estimate. A public adjuster can take over most of the homeowner’s side, including paperwork, communication, and negotiations.
- Reviewing your policy language in detail
- Preparing their own damage estimate
- Tracking additional living expenses if your home is unlivable
- Handling correspondence and negotiating directly with the insurer
6. Licensing and Oversight
Both types of adjusters must hold an adjuster’s license in most states, but the rules vary by state law. Public adjusters are regulated by state insurance departments, which often set rules on contracts, fees, and conduct. Before hiring one, ask for their state license number and verify it.
These differences don’t mean one adjuster is always better than the other. They simply help you understand what to expect from each person involved in your claim.
The Different Types of Insurance Adjusters
Not all adjusters in the insurance industry have the same title or role. Knowing the common types helps you understand who you’re talking to and how decisions on your claim get made.
Staff Adjusters
Staff adjusters are full-time employees of an insurance company. They handle claims directly and follow their employer’s procedures and guidelines.
Independent Adjusters
Independent adjusters work for insurance companies on a contract basis, often after a major storm when claim volume spikes and staff adjusters can’t keep up with demand. Despite the name, they still represent the insurer, not the homeowner.
Desk Adjusters
Desk adjusters review claims from the office rather than visiting your property. They often look over photos, estimates, and reports submitted by field adjusters before a final decision is made.
Public Adjusters
Public adjusters work only for the policyholder. They’re hired directly by homeowners and business owners for residential and commercial claims, from storm-related property damage to fire damage. Many belong to professional groups such as the National Association of Public Insurance Adjusters.
Understanding these roles can clear up a lot of confusion, especially when several people from the insurance company or other third parties contact you about the same claim. If you’re ever unsure who someone represents, it’s perfectly reasonable to ask.
When a Public Adjuster Makes Sense and Where Your Roofer Fits In
Many claims are handled smoothly without a public adjuster, while others benefit from extra help. Knowing the difference can save you money and frustration.
Situations Where a Public Adjuster May Help
- Large or complex claims: Extensive damage to the roof, siding, and interior may benefit from professional negotiation that helps level the playing field.
- Disputed or underpaid claims: If your claim settlement offer seems far below repair estimates, a reputable public adjuster can challenge it. If a dispute escalates, an attorney may be the next step.
- Limited time or experience: Busy homeowners may prefer to hand off paperwork and communication.
Situations Where You May Not Need One
- Small, straightforward claims: A fee may eat up much of a modest payout.
- Clear, fair offers: If the insurer’s estimate matches your roofer’s findings, extra help may not add much value.
- Damage close to your deductible: If repair costs barely exceed your deductible, filing a claim at all may not make sense.
Comparing the Roles in a Roof Claim
| Role | Who They Work For | What They Do in a Roof Claim |
| Insurance adjuster | Your insurance company | Inspects damage and estimates the covered amount |
| Public adjuster | You, the policyholder | Documents losses and negotiates the settlement |
| Roofing contractor | You, the homeowner | Inspects, documents damage, and completes repairs |
A trusted roofing contractor brings construction knowledge to the table even though they don’t negotiate your claim. In many states, contractors aren’t permitted to negotiate on a homeowner’s behalf, but they can inspect your roof, document damage, and meet with the adjuster to point out issues. They can also flag code upgrades your home may need and provide estimates based on current pricing, which matters if your policy includes code upgrade coverage. Homeowners in Johnson Creek and surrounding areas often find that having an experienced roofer on site during the adjuster’s visit helps make sure nothing gets overlooked.
Frequently Asked Questions About Public Adjusters vs Insurance Adjusters
Adjusters play a big role in how your claim is handled, so it’s natural to have questions. Here are simple answers to some of the most common ones.
Does the insurance adjuster work for me?
No. The insurance adjuster represents your insurance carrier. They’re expected to follow your policy and the law, but their role is to evaluate the claim for the insurer.
How much does a public adjuster cost?
Most public insurance adjusters charge a percentage of the settlement, though some use a flat fee. The exact rate varies, and some states cap the fees they can charge, so review the contract carefully before signing.
Will hiring a public adjuster guarantee a bigger payout?
No. A public adjuster may help uncover missed damage or negotiate a better settlement, but they can’t get you more than your insurance policy allows, and results vary.
Can I hire a public adjuster after my claim has been settled?
In some cases, yes, especially if the claim can be reopened or you’re disputing the amount. Check your policy and state rules for any deadlines.
Can my roofing contractor talk to the insurance adjuster?
Yes. Your roofer can meet with the adjuster, share findings, and explain the damage. In many states, however, contractors can’t negotiate the claim for you.
Every claim is unique, and the right approach depends on your damage, your policy, and your comfort level with the process. A local roofing professional can help you understand what your roof needs before you make any decisions.
Get Help Navigating Your Roof Damage Claim
Knowing the difference between a public adjuster and an insurance adjuster puts you in a stronger position when storm damage hits. With clear expectations and the right team in your corner, the claims process becomes much easier to manage. Classic Construction helps homeowners in Johnson Creek and surrounding areas inspect and document roof damage, meet with adjusters, and complete quality repairs. If your roof has been damaged in a recent storm, contact us today to schedule an inspection and get honest guidance on your next steps.


